Fino Bank AePS Service 2027: Cash Withdrawal, Cash Deposit, Fingerprint Banking, Merchant Commission & Benefits
Introduction: What Is Fino Bank AePS Service 2027?
Banking services have become easier and more accessible with digital payment technology. Today, customers do not always need to visit a bank branch or use an ATM to access basic banking services. They can visit an authorised banking agent or merchant outlet and complete transactions using their Aadhaar number and fingerprint.
One of these services is called AePS (Aadhaar Enabled Payment System).
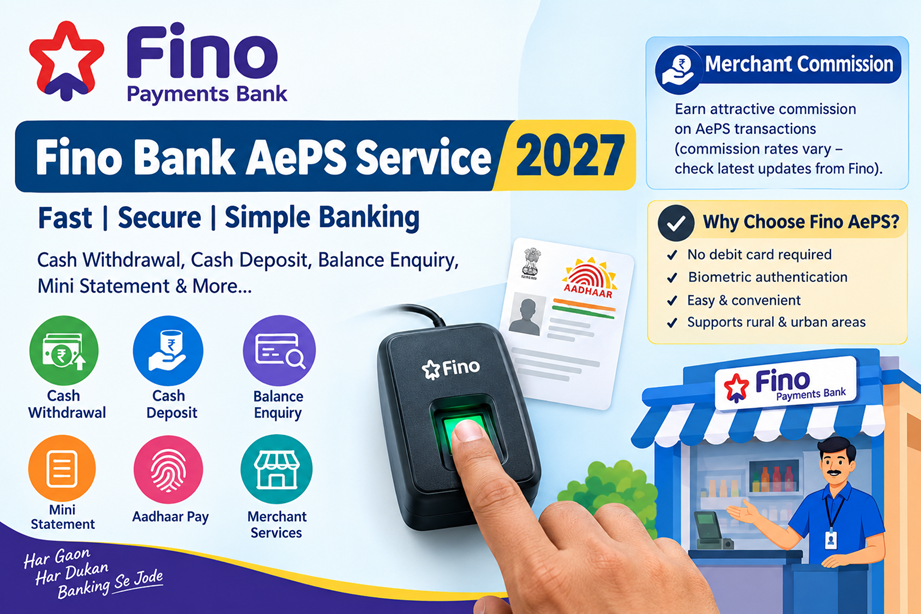
Fino Payments Bank provides AePS-related banking services through its merchant network. With Fino AePS services, eligible customers can access banking facilities such as cash withdrawal, cash deposit, balance enquiry and mini statements, subject to service availability and transaction eligibility.
For small shop owners, retailers, CSC operators and banking agents, AePS can also create an additional business opportunity. Merchants can provide convenient banking services to local customers and earn commissions according to applicable merchant schemes.
In this guide, we will explain everything about Fino Bank AePS Service 2027, including how to withdraw money, how to deposit cash using fingerprint authentication, commission opportunities, transaction types and frequently asked questions.
1. What Is AePS?
AePS stands for Aadhaar Enabled Payment System.
It is a bank-led payment system developed to make basic banking services accessible through Aadhaar authentication.
Customers can visit an authorised Business Correspondent (BC) or merchant outlet, provide their Aadhaar number, select their bank and authenticate the transaction using a registered biometric device.
The transaction is processed through the participating banking network.
How Does AePS Work?
The process is simple:
- A customer visits an authorised AePS merchant.
- The customer provides their Aadhaar number.
- The merchant selects the customer’s bank.
- The customer selects the required banking service.
- The customer places their finger on a registered biometric scanner.
- The system verifies the biometric authentication.
- The transaction is processed.
- The customer receives a transaction confirmation or receipt.
AePS is particularly useful in villages, small towns and areas where access to traditional bank branches and ATMs may be limited.
2. What Is Fino Bank AePS Service?
Fino Payments Bank offers banking and payment services through its merchant network.
Fino merchants can provide different services, including:
- AePS cash withdrawal.
- AePS cash deposit.
- Balance enquiry.
- Mini statement.
- Micro ATM services.
- Domestic money transfer.
- Aadhaar Pay.
- Bill payments and mobile recharges.
The availability of individual services depends on merchant activation, banking partner support, transaction limits and applicable operational rules.
Official website: https://www.fino.bank.in/
3. Types of Fino AePS Services in 2027
Fino AePS offers different types of banking transactions.
A. AePS Cash Withdrawal
Cash withdrawal is one of the most commonly used AePS services.
Customers can withdraw money from their Aadhaar-linked bank account by visiting an authorised merchant.
For example, suppose a customer needs ₹2,000 but there is no ATM nearby. They can visit a Fino merchant, provide their Aadhaar number and bank details, and authenticate the withdrawal using their fingerprint.
After successful verification, the merchant provides the customer with cash.
Benefits:
- No debit card is required.
- Convenient banking access.
- Fingerprint-based authentication.
- Useful for rural and semi-urban customers.
- Saves time and travel to a bank branch.
B. AePS Cash Deposit
Cash deposit is another important banking service.
Customers can deposit physical cash into an eligible bank account through an authorised merchant outlet.
Fino also offers a specific service called AePS 3-Party Cash Deposit, which allows cash deposits into the depositor’s own or another beneficiary’s bank account through participating Fino merchant points.
The depositor must complete the required registration and biometric authentication.
Fino’s published service information specifies the following conditions for its 3-party cash deposit service:
- One-time e-KYC registration using the depositor’s mobile number and Aadhaar number.
- One-time registration fee: ₹10.
- Transaction service charge: 1% of the transaction amount.
- Maximum per transaction: ₹10,000.
- Daily limit: ₹50,000.
- Monthly limit: ₹2,00,000.
These are published service terms and should be reconfirmed before making a transaction, as charges and limits may change.
C. AePS Balance Enquiry
Customers can check their bank account balance without visiting a bank branch.
The customer provides their Aadhaar number and bank selection, then completes fingerprint authentication.
The system displays the available balance if the transaction is successful.
D. AePS Mini Statement
A mini statement helps customers check their recent banking transactions.
Customers can use this service to understand their recent withdrawals, deposits and other account activities.
Fino’s AePS information describes mini statements containing up to the last nine transactions.
E. Aadhaar Pay
Aadhaar Pay allows customers to make payments to participating merchants using their Aadhaar number and biometric authentication.
It is different from cash withdrawal and cash deposit. It is primarily a merchant payment collection facility.
4. How to Withdraw Money Through Fino AePS Using Fingerprint
AePS cash withdrawal is simple and convenient.
Follow these steps:
- Visit an authorised Fino AePS merchant.
- Ask for the AePS cash withdrawal service.
- Provide your Aadhaar number.
- Select your bank name.
- Enter the amount you want to withdraw.
- Check the transaction details.
- Place your finger on the biometric scanner.
- Complete fingerprint authentication.
- Wait for the transaction response.
- Collect your cash and transaction receipt after successful completion.
Example:
If you want to withdraw ₹3,000, the merchant enters ₹3,000 into the AePS system. After successful biometric authentication and transaction approval, the merchant gives you ₹3,000 in cash.
Important: Always check the transaction status before accepting or handing over cash. Never share your Aadhaar OTP, banking PIN or other confidential credentials with anyone.
5. How to Deposit Cash Through Fino AePS Using Fingerprint
Cash deposit through biometric authentication is a useful service for customers who want to deposit cash without visiting a bank branch.
Fino’s 3-party AePS cash deposit service allows eligible customers to deposit cash into their own or another beneficiary’s bank account through participating merchant points.
Step-by-Step Cash Deposit Process
- Visit an authorised Fino merchant offering the 3-party cash deposit service.
- Complete the required one-time e-KYC registration if you are a new depositor.
- Provide the required Aadhaar and mobile number details.
- Select the cash deposit service.
- Enter the beneficiary’s bank account details as required by the system.
- Enter the deposit amount.
- Provide the cash to the merchant.
- Complete biometric authentication using your fingerprint.
- Wait for successful transaction confirmation.
- Collect the transaction receipt and verify the beneficiary account credit.
Example:
Suppose you want to deposit ₹5,000 into a family member’s eligible bank account. You can visit a participating Fino merchant, complete the required process and authenticate the transaction using your fingerprint.
The cash deposit will be processed according to the service’s transaction rules.
Important Cash Deposit Conditions
According to Fino’s published 3-party cash deposit service details:
| Particulars | Published limit/charge |
|---|---|
| One-time registration fee | ₹10 |
| Transaction service charge | 1% |
| Maximum per transaction | ₹10,000 |
| Daily transaction limit | ₹50,000 |
| Monthly transaction limit | ₹2,00,000 |
Confirm the latest applicable terms with Fino before proceeding.
6. What Is Fino AePS Merchant Commission in 2027?
One of the biggest questions among retailers and banking agents is:
How much commission can a Fino AePS merchant earn per transaction?
Fino provides merchant earning opportunities through its banking and payment services. Merchants may earn incentives or commissions depending on the transaction type, monthly performance, applicable scheme and merchant category.
However, the exact Fino AePS merchant commission for 2027 should be confirmed through the current merchant portal or authorised Fino representative.
Fino’s older merchant brochures published transaction-based payout slabs. These are historical examples, not confirmed 2027 rates.
Historical AePS Commission Example
An older Fino merchant brochure published the following AePS payout structure:
| Transaction amount slab | Published effective payout example |
|---|---|
| ₹100–₹999 | ₹3.50 |
| ₹1,000–₹1,499 | ₹4.50 |
| ₹1,500–₹1,999 | ₹5.50 |
| ₹2,000–₹2,499 | ₹6.50 |
| ₹2,500–₹2,999 | ₹7.50 |
| ₹3,000–₹3,999 | Up to ₹13.50 |
| ₹4,000–₹7,999 | ₹9.50 |
| ₹8,000–₹10,000 | ₹9.50–₹12.50 |
The payout varied by the scheme option. The figures above must not be treated as the current 2027 commission chart.
How Much Can a Fino Merchant Earn?
Merchant earnings depend on:
- Number of successful transactions.
- Transaction amount and type.
- Applicable commission slab.
- Monthly transaction volume.
- Promotional schemes.
- Merchant eligibility and activation.
For example, a merchant who handles more successful customer transactions may have a greater earning opportunity than a merchant with very few transactions. Actual income is not guaranteed.
How to Check the Latest Fino AePS Commission?
Merchants should:
- Log in to their authorised Fino merchant platform.
- Check the latest commission or payout section.
- Review current merchant circulars.
- Contact the Fino distributor or relationship manager.
- Confirm whether the commission applies to withdrawal, deposit, balance enquiry or mini statement separately.
Always calculate earnings using the latest applicable payout chart.
7. Difference Between AePS and Micro ATM
Many customers and merchants confuse AePS with Micro ATM services.
Both can provide cash withdrawal facilities, but their transaction methods differ.
| Feature | AePS | Micro ATM |
|---|---|---|
| Authentication | Aadhaar biometric | Usually debit card and PIN |
| Debit card | Not required | Generally required |
| Main purpose | Aadhaar-based banking | Card-based banking |
| Cash withdrawal | Yes | Yes |
| Balance enquiry | Yes | Supported |
| Merchant device | Registered biometric device | Micro ATM device |
| Customer identification | Aadhaar authentication | Card and PIN authentication |
Fino merchants may provide both services, depending on their activation and equipment.
8. Requirements to Become a Fino AePS Merchant
If you want to start providing AePS services, you need to apply through an authorised Fino merchant onboarding channel.
Common requirements may include:
- Aadhaar card.
- PAN card.
- Valid mobile number.
- Bank account details.
- Shop or business details.
- Identity and address proof.
- Other documents required during onboarding.
Equipment Required
For biometric AePS transactions, an authorised and registered biometric device is required.
Examples of biometric device brands include:
- Mantra.
- Aratek.
- Evolute.
The device must meet the applicable RD service and authentication requirements and be compatible with the authorised merchant platform.
Benefits of Becoming a Fino Merchant
- Additional income opportunities.
- Opportunity to attract more customers.
- Multiple banking and payment services.
- Better customer convenience.
- Potential to build a local banking service outlet.
- Access to other merchant products and services.
9. Benefits of Fino AePS Services for Customers
AePS is especially helpful for customers who may not have convenient access to traditional banking facilities.
1. Convenient Banking
Customers can access basic banking services through authorised merchant outlets.
2. No Debit Card Required
Cash withdrawal and other eligible transactions can be completed using Aadhaar authentication.
3. Fingerprint Authentication
Biometric authentication helps verify the customer’s identity.
4. Saves Time
Customers may avoid travelling to a distant bank branch or ATM.
5. Rural Banking Support
AePS helps extend basic banking services to underserved locations.
6. Multiple Banking Facilities
Depending on availability, customers can withdraw cash, deposit money, check balances and request mini statements.
10. Safety Tips While Using Fino AePS
Customers should follow these safety precautions:
- Use only authorised AePS merchants.
- Check the transaction amount before authentication.
- Never share your Aadhaar OTP or bank PIN.
- Collect your receipt or transaction reference.
- Verify the bank account credit after a deposit.
- Do not authenticate transactions you did not request.
- Report unauthorised transactions immediately.
- Keep your Aadhaar and banking information secure.
If a transaction fails but money is debited, keep the transaction reference and raise a complaint through the relevant bank or authorised service provider.
11. Why Is Fino AePS Important in 2027?
Digital banking continues to expand across India. However, many people still prefer visiting a nearby shop or banking agent for cash-related services.
AePS connects Aadhaar-based authentication with basic banking services and helps customers access their bank accounts through authorised service points.
For shop owners, offering AePS can help diversify their business and provide an additional service to existing customers.
For customers, it offers an alternative way to access basic banking facilities without depending entirely on ATMs or bank branches.
Frequently Asked Questions (FAQs)
1. What is Fino Bank AePS Service?
Fino Bank AePS is an Aadhaar-based banking service that allows eligible customers to access supported banking facilities through authorised merchant outlets using biometric authentication.
2. Can I withdraw money through Fino AePS using my fingerprint?
Yes. Eligible customers can withdraw cash from their Aadhaar-linked bank accounts through an authorised AePS merchant after successful fingerprint authentication.
3. Can I deposit cash through Fino AePS?
Yes. Fino offers an AePS 3-party cash deposit service through participating merchant points, subject to registration, eligibility and transaction limits.
4. What is the Fino AePS commission in 2027?
The exact 2027 commission depends on the latest merchant payout scheme. Merchants should check the current commission chart through their authorised Fino merchant platform or representative.
5. How much is the Fino AePS cash deposit charge?
Fino’s published 3-party cash deposit service details mention a 1% transaction service charge and a one-time ₹10 registration fee. Verify the latest charges before transacting.
6. What is the maximum Fino AePS cash deposit limit?
Fino’s published 3-party cash deposit terms mention ₹10,000 per transaction, ₹50,000 daily and ₹2,00,000 monthly. Current limits should be confirmed with Fino.
7. Is Aadhaar linking compulsory for AePS?
Yes. The customer’s Aadhaar must be linked to the bank account being accessed through AePS.
8. Is a debit card required for AePS cash withdrawal?
No. AePS cash withdrawal uses Aadhaar and biometric authentication rather than requiring a debit card.
9. Can I check my bank balance through Fino AePS?
Yes. Customers can use the balance enquiry facility through an authorised AePS merchant.
10. What is an AePS mini statement?
It is a facility that allows customers to view recent account transactions. Fino’s service information describes mini statements of up to nine transactions.
11. Which biometric device is required for Fino AePS?
An authorised registered biometric device compatible with the merchant platform is required. Device examples include Mantra, Aratek and Evolute.
12. Can I deposit money into another person’s bank account?
Fino’s 3-party cash deposit service supports deposits into the depositor’s own or another beneficiary’s eligible bank account, subject to its registration and transaction requirements.
13. What should I do if my AePS transaction fails?
Keep your transaction reference, check your bank account, and raise a complaint with the relevant bank or authorised merchant service provider if money has been debited without the transaction being completed.
14. How can I become a Fino AePS merchant?
You can apply through Fino’s official merchant onboarding process. Approval, documentation, training and service activation requirements apply.
15. Is Fino AePS safe?
AePS uses biometric authentication and the participating banking network. Customers should transact only through authorised merchants and verify every transaction.
Conclusion
Fino Bank AePS Service 2027 offers an important way to make basic banking facilities more accessible through Aadhaar-based biometric authentication.
Services such as cash withdrawal, cash deposit, balance enquiry and mini statements can benefit customers, particularly in rural and semi-urban areas.
For retailers and small business owners, becoming an authorised Fino merchant can provide additional business opportunities through banking and payment services.
Before using or offering AePS services, always check the latest transaction limits, service charges, commission structure and eligibility conditions.
Explore more business, banking and digital payment information on VyaparGrow.in.