Fino Micro ATM: What Is It, How Does It Work, Benefits, Uses and How to Become a Fino Merchant
Introduction
Access to banking services is important for everyone, whether they live in a large city, a small town, or a rural village. However, visiting a bank branch or finding a nearby ATM can sometimes be difficult. This is where a Micro ATM becomes useful.
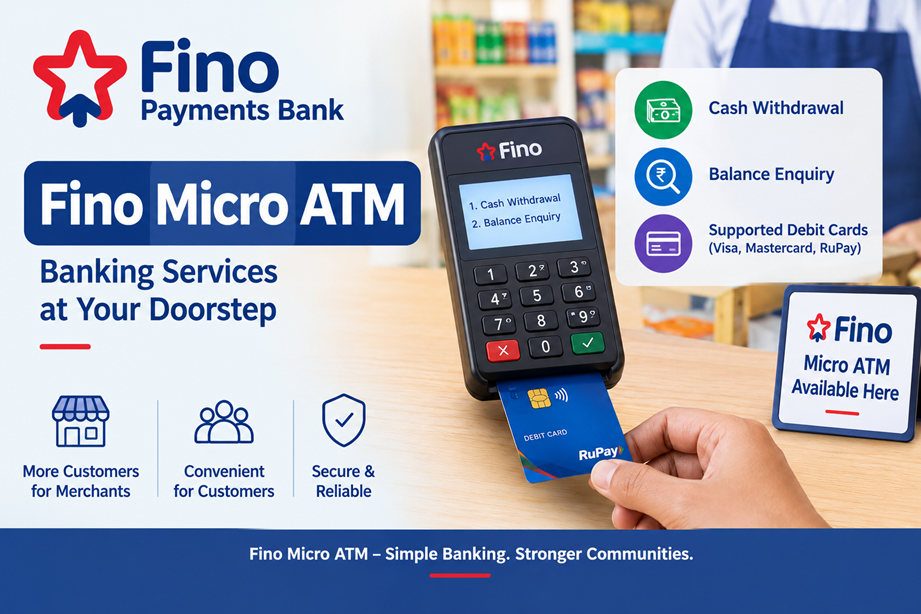
Fino Micro ATM is a banking service offered through Fino Payments Bank’s merchant network. It allows customers to access certain banking services, particularly cash withdrawals and balance enquiries, through an authorised merchant outlet using a debit card and PIN.
For shopkeepers, retailers, and small business owners, becoming a Fino merchant can provide an opportunity to offer additional services, attract more customers, and earn commissions on eligible transactions.
In this guide, we will explain what a Fino Micro ATM is, why it is needed, how it works, its main benefits, and how you can explore becoming a Fino merchant.
1. What Is Fino Micro ATM?
A Fino Micro ATM is a compact, electronic banking device that allows customers to perform selected banking transactions at an authorised merchant’s shop instead of visiting a traditional ATM or bank branch.
It works through a banking network and a connected device operated by an authorised merchant. Customers generally use their debit card and PIN to authenticate eligible transactions.
Fino Payments Bank provides Micro ATM services as part of its broader merchant banking solutions.
For example, suppose a customer needs ₹2,000 in cash but there is no ATM nearby. If an authorised Fino Micro ATM merchant is available locally, the customer may be able to withdraw cash through that outlet, subject to transaction limits, available cash, and service availability.
This makes Micro ATM services particularly useful in areas where access to conventional banking facilities is limited.
2. Why Is Fino Micro ATM Needed?
Although digital payments are growing rapidly in India, cash remains important for many everyday transactions. People may need cash to purchase groceries, pay local service providers, travel, or meet other immediate expenses.
A Micro ATM helps bridge the gap between traditional banking facilities and local communities.
Major reasons why Micro ATM services are useful
1. Convenient access to cash
Customers may be able to withdraw cash from an authorised merchant near their home or workplace instead of travelling to an ATM.
2. Support for rural and semi-urban areas
In areas where bank branches and ATMs are less accessible, authorised merchant outlets can provide an additional channel for basic banking services.
3. Saves time and travel expenses
Customers can potentially save time and transportation costs by accessing services at nearby shops.
4. Supports small merchants
Retailers can expand their services beyond selling products by providing eligible banking facilities to customers.
5. Encourages financial inclusion
Merchant-based banking services can help bring basic financial services closer to people who may face difficulties accessing traditional banking infrastructure.
6. Offers an additional service for cash-based communities
Small traders, daily-wage earners, and customers who regularly use cash may find nearby withdrawal facilities convenient.
3. What Are the Uses of Fino Micro ATM?
Fino Micro ATM is primarily intended to provide selected banking transactions through an authorised merchant outlet.
Its main uses include:
Cash withdrawal
Customers can withdraw cash from eligible bank accounts using a supported debit card and PIN, subject to applicable transaction limits and service conditions.
Balance enquiry
Customers can check the available balance in their bank accounts through the supported Micro ATM service.
Banking convenience at local shops
Customers can access eligible services at participating merchant outlets during their operating hours.
Service for customers of different banks
Fino’s Micro ATM information states that supported debit cards from networks such as Visa, Mastercard, and RuPay can be used. Actual availability depends on the supported service and transaction rules.
Additional business service for retailers
A merchant can offer Micro ATM facilities alongside their regular business activities, helping customers access banking services at a familiar local outlet.
Important: Micro ATM and Aadhaar Enabled Payment System (AePS) are different transaction methods. A standard Micro ATM transaction generally uses a debit card and PIN, while AePS uses Aadhaar-based authentication through an authorised banking channel.
4. How Does Fino Micro ATM Work?
The process is straightforward when the device, banking network, and merchant service are operational.
- Visit an authorised merchant: Find a participating Fino Micro ATM outlet.
- Request a transaction: Tell the merchant whether you want to withdraw cash or check your balance.
- Use your debit card: Insert, swipe, or otherwise present the supported card as instructed by the device.
- Enter your PIN securely: Enter your card PIN yourself. Never disclose it to the merchant or another person.
- Wait for confirmation: The system processes the transaction through the banking network.
- Collect cash, if applicable: For a successful withdrawal, collect the cash and transaction receipt or reference details if provided.
- Verify the transaction: Check the amount and your bank’s SMS or account notification, if available.
If a transaction fails but money appears to have been deducted, keep the transaction details and contact the relevant bank or Fino support channel for assistance.
5. What Is a Fino Merchant?
A Fino merchant is an approved retailer or business operator who provides authorised financial services through Fino’s merchant network.
Instead of operating only as a conventional shopkeeper, a Fino merchant may be able to offer eligible banking and payment services to customers.
Fino identifies businesses such as the following as potential merchant outlets:
- Kirana and general stores
- Mobile phone shops
- Pharmacies
- Dairy shops
- Bakeries
- Photocopy and stationery shops
- Government service centres
- Other eligible retail businesses
The services available depend on the merchant’s approval, onboarding, location, and the products enabled for their account.
6. Benefits of Becoming a Fino Micro ATM Merchant
For an existing shopkeeper, adding banking services may create another way to serve local customers.
1. Opportunity to earn commissions
Eligible Micro ATM transactions may generate commissions for the merchant under the applicable Fino scheme. Actual earnings depend on the transaction type, current commission structure, and completed transaction volume.
2. Attract more customers
People visiting your shop for cash withdrawals or balance enquiries may also purchase other products or use additional services.
3. Increase customer loyalty
Offering useful services locally can help build stronger relationships with customers and encourage repeat visits.
4. Add services to an existing business
A merchant may be able to combine banking services with the shop’s existing activities rather than relying on product sales alone.
5. Provide multiple financial services
Depending on eligibility and activation, Fino’s merchant offering may include services such as Micro ATM, AePS, domestic money transfers, bill payments, recharges, and other approved products.
6. Help customers in your local community
A merchant can make selected banking services more accessible to nearby residents, including people who may otherwise need to travel farther.
7. Receive onboarding guidance and support
Fino describes training and support as part of its merchant offering. Applicants should confirm the current onboarding process and support arrangements with Fino before joining.
Remember: Becoming a merchant does not guarantee a fixed income. Earnings depend on customer demand, transaction volume, applicable commissions, costs, and service availability.
7. How Much Can a Fino Micro ATM Merchant Earn?
Merchant income depends on the number of eligible transactions completed and the commission applicable to each transaction.
For example, consider this illustration:
| Particulars | Example amount |
|---|---|
| Eligible transactions per day | 20 |
| Assumed average commission per transaction | ₹5 |
| Illustrative daily commission | ₹100 |
| Illustrative monthly commission for 30 days | ₹3,000 |
These figures are only a mathematical example, not Fino’s official commission rates or an income guarantee. Actual commissions may be higher or lower, and the current scheme should be confirmed directly with Fino.
A merchant’s overall business may also benefit from additional customer visits, but those sales are separate from Micro ATM commissions.
Before starting, ask about commission rates, device or onboarding charges, settlement procedures, cash requirements, applicable taxes, and any other operating expenses.
8. How to Become a Fino Micro ATM Merchant
If you operate a shop and want to explore offering Micro ATM services, you can contact Fino through its official merchant channels.
Follow these general steps:
Step 1: Check your eligibility
Confirm whether your shop type, business location, and existing business documents meet the current requirements.
Step 2: Contact Fino Payments Bank
Visit the official Fino merchant services page:
You can also contact Fino’s merchant helpline to ask about Micro ATM onboarding.
Step 3: Prepare the required documents
Depending on your business and the onboarding process, you may be asked to provide documents such as:
- PAN card
- Valid identity proof
- Address proof
- Shop or business details
- Bank account details
- Other documents requested by Fino
The final document checklist must be confirmed with Fino.
Step 4: Understand the charges and commission structure
Before accepting an offer, ask for the current commission schedule, device cost if any, transaction rules, settlement arrangements, and applicable charges in writing.
Step 5: Complete verification and onboarding
Submit the application and complete the required verification and training process.
Step 6: Activate the service
Once approved, follow Fino’s instructions to activate the service and learn how to process transactions securely.
Step 7: Inform local customers
Display approved service information at your shop and explain the services you can provide. Never advertise a transaction or feature that has not been activated for your outlet.
9. Is Fino Micro ATM Suitable for Small Shopkeepers?
Fino Micro ATM may be worth exploring if you already operate a retail outlet and want to add financial services.
It may be particularly relevant for businesses located in areas where customers need convenient access to cash or basic banking services.
However, it is important to evaluate your location and expected demand before investing.
Consider these questions:
- Are there enough potential customers in your area?
- Are ATMs or bank branches difficult to access nearby?
- Can you maintain sufficient cash for customer withdrawals?
- Are the commissions appropriate for your expected transaction volume?
- Do you understand the device charges, settlement process, and service rules?
- Can you follow the required security and compliance procedures?
If the expected customer demand is low or operating costs are high, the service may not be profitable. Compare the terms carefully before making a decision.
10. Safety Tips for Customers and Merchants
Banking convenience must be accompanied by safe transaction practices.
- Never share your debit card PIN, OTP, or banking password with anyone.
- Enter your PIN privately and shield the keypad where possible.
- Check the amount before confirming a transaction.
- Keep the receipt or transaction reference for future complaints.
- Never issue cash against a transaction that has not been confirmed as successful.
- If cash is not dispensed but the account is debited, report the issue promptly through official support channels.
- Use only authorised devices and merchant outlets.
- Confirm charges before completing a transaction.
- Avoid sharing customers’ account information or transaction details with unauthorised people.
Conclusion
Fino Micro ATM is a convenient way to access selected banking services through an authorised merchant outlet. It can help customers access cash and check their account balances while giving eligible shopkeepers an opportunity to expand their services.
For retailers, the main potential benefits include transaction-based commissions, more customer visits, and the ability to offer additional financial services. However, actual earnings and operating requirements depend on Fino’s current terms and the merchant’s business location.
If you want to become a Fino Micro ATM merchant, review the official merchant information, verify all charges and commissions, and complete the authorised onboarding process before starting.
For more business ideas, business tools, and business growth information, explore VyaparGrow.com.
Frequently Asked Questions (FAQs)
1. What is Fino Micro ATM?
Fino Micro ATM is a banking service that allows customers to perform supported transactions, such as cash withdrawals and balance enquiries, through an authorised merchant using a supported debit card and PIN.
2. What is the main use of a Fino Micro ATM?
Its main uses are cash withdrawal and balance enquiry through participating merchant outlets, subject to the services enabled and applicable limits.
3. Who can become a Fino Micro ATM merchant?
Eligible shopkeepers and retailers, including kirana stores, mobile shops, pharmacies, dairy shops, and other businesses, can enquire about joining Fino’s merchant network. Approval is subject to Fino’s requirements.
4. How does a Fino Micro ATM merchant earn money?
An eligible merchant may receive commissions for completed transactions according to the applicable commission scheme. Income varies with transaction volume and the current terms.
5. Is there a fixed monthly income from Fino Micro ATM?
No fixed monthly income should be assumed. Earnings depend on customer demand, transaction volume, applicable commissions, and operating costs.
6. Which cards can be used at a Fino Micro ATM?
Fino’s published Micro ATM information lists supported Visa, Mastercard, and RuPay debit cards. Availability can depend on the service and transaction conditions.
7. What is the transaction limit for Fino Micro ATM?
Fino’s published Micro ATM page lists a minimum transaction amount of ₹100 and a maximum transaction limit of ₹10,000. Customers should confirm the current per-transaction and daily limits with Fino before transacting, as limits and conditions can change.
8. Is Fino Micro ATM the same as AePS?
No. Micro ATM generally uses a debit card and PIN, whereas AePS uses Aadhaar-based authentication through an authorised banking channel. They are different services.
9. What documents are required to become a Fino merchant?
Documents may include PAN, identity proof, address proof, and business details. The exact requirements depend on Fino’s current onboarding policy and the applicant’s circumstances.
10. How can I apply to become a Fino Micro ATM merchant?
Visit https://www.fino.bank.in/merchant-services or contact Fino’s official merchant support team to check eligibility and start the application process.
11. Does a Fino merchant need to keep cash available?
A merchant offering cash withdrawals generally needs sufficient cash to serve customers. The merchant should understand cash management, settlement procedures, and the applicable operating requirements before activation.
12. Where can I get help with a Fino Micro ATM transaction?
Contact Fino through its official support channels or the relevant bank if your transaction involves an account held with another bank. Keep your transaction reference, date, amount, and any receipt available when reporting the issue.